Program 03 · Manufactured & Mobile
The homes other lenders won't touch.
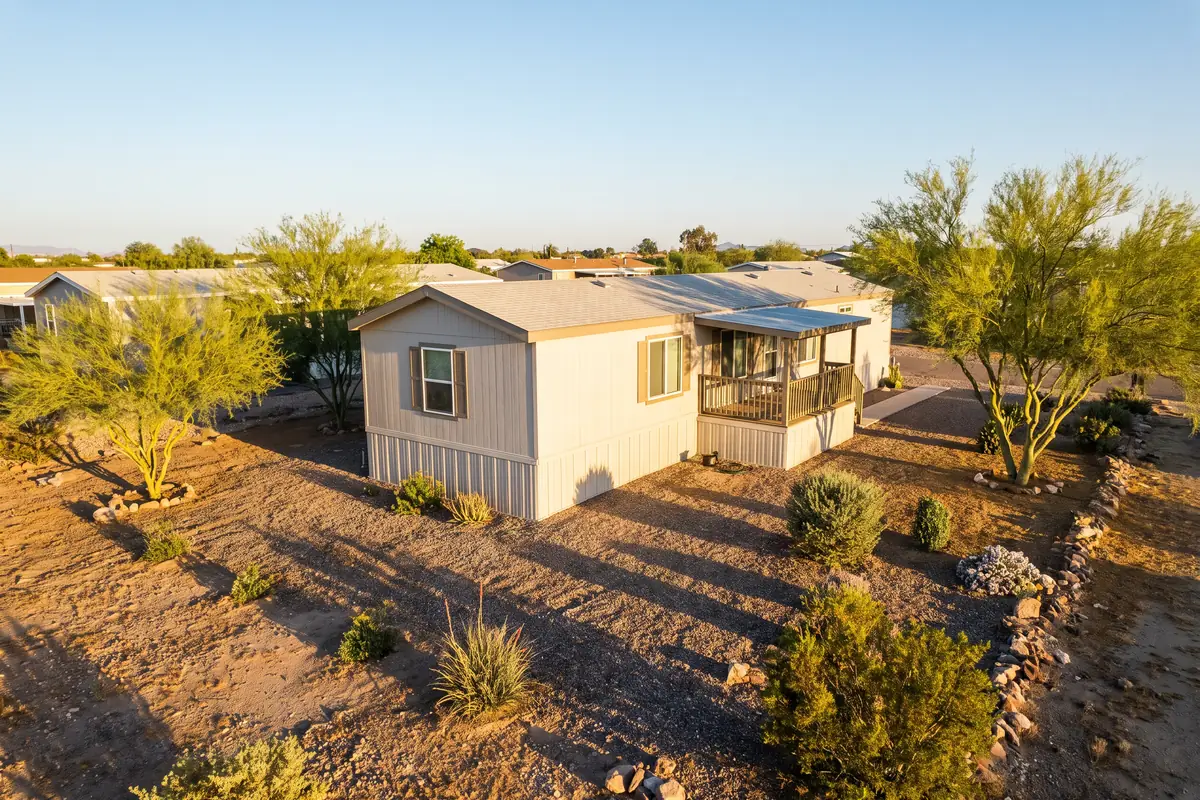
Most banks and hard money lenders decline manufactured and mobile homes outright. Versara doesn't. We finance pre-1976, pre-HUD-code homes, single-wides, and manufactured homes that need to be affixed to close.
*Starting rate and maximum leverage are for qualified transactions and subject to underwriting; actual rate, LTV, and LTC vary by deal, program, and state. Business-purpose loans to entities secured by non-owner-occupied property only. Terms subject to underwriting; rates and terms vary by deal and state. BK #0944451.
Versara snapshot
Updated August 202601 · Program facts
Program guidelines
Versara lends on mobile and manufactured homes, including the ones most banks turn down. What follows is the current guideline sheet for this program.
Mobile & Manufactured Home Loans
- Property Types:
- Mobile and manufactured homes
- Loan Purposes:
- Business-purpose purchase and refinance transactions
- Arizona Coverage:
- Statewide, including rural areas
- Loan Purpose Restriction:
- Business and investment purposes only
Versara Term Sheet
- Interest rate:
- 12%
- Origination:
- 1 point at closing
- Doc fee:
- $495
- Down payment:
- Minimum 20% down
- Term:
- 6–12 months
- Home requirement:
- Must be affixed to a permanent foundation on the real property
- Title requirement:
- The home must be titled as real property. The vehicle or chattel title has to be surrendered and the home recorded with the land before closing. We do not lend on chattel-titled homes
- Eligible homes:
- Pre-1976 (pre-HUD-code), single-wides, and previously un-affixed manufactured homes
- Borrower:
- Business entities (LLC, corporation, partnership), non-owner-occupied only
- Credit:
- Bad credit, bankruptcy, foreclosure, and short sales workable, since we underwrite on equity
- Speed:
- Same-day qualification, funding in as little as 24 hours on qualified products
Terms, rates, and fees are subject to change without notice and are not a commitment to lend. All loans are for business or investment purposes only, subject to underwriting approval and executed documentation. Rates and terms vary by deal and state.
02 · How much we lend
Maximum leverage
| Scenario | Max LTP Residential | Max LTV 1st Lien Residential |
|---|---|---|
| Purchase Short-Term (no Value-Add) | 80% | — |
| Refinance Short-Term (no Cash Out) | — | 70% |
| Refinance & Cash Out Short-Term | — | 70% |
Scroll the table sideways to see every column.
03 · Fit check
Which deals we fund
Common Loan Scenarios
- Investor purchasing a single-family property to renovate and resell
- Investor acquiring a residential property that requires repairs or renovation
- Investor needing bridge financing for a time-sensitive real estate acquisition
- Property owner completing a cash-out refinance to access equity for business purposes
- Business-purpose borrower seeking a second mortgage behind an existing first mortgage
- Investor purchasing or refinancing a mobile or manufactured home
- Investor financing an investment property in a rural or remote Arizona market
- Borrower with a low credit score seeking asset-based real estate financing
Scenarios Not Considered
- Purchasing a property with no money down
- 100% financing
- Consumer-purpose loans
- Ground-up construction loans
- Consumer-purpose residential loans
- Owner-occupied home purchase financing
04 · What it costs
Fees
- Processing Fee:
- Our origination, processing, underwriting and doc fees combined are almost always under 1% of the loan amount for a regular fix and flip loan.
- Escrow Fee:
- normal escrow and title fees when you purchase a property or do a refinance
- Title Fee:
- normal escrow and title fees when you purchase a property or do a refinance
Additional details
While our fee is typically $995 to $1,995 for senior (1st lien) loans, it can be higher in some cases. The minimum fee for 2nd mortgages is $5,000.
Last updated: September 14, 2026
Before you apply.
All FAQsDo you finance pre-1976 mobile homes?
Yes. Versara lends on pre-1976, pre-HUD-code manufactured and mobile homes most banks and hard money lenders won't touch, plus single-wides and other manufactured housing that doesn't fit a conventional file.
Does the home need to be affixed to the land?
Yes. The home must be affixed to a permanent foundation on the real property to secure the loan. We work with un-affixed homes too. It just needs to be affixed by the time we close.
Why do banks decline manufactured homes?
Banks treat manufactured and mobile homes as riskier collateral: appraisal comps are thin, resale value is harder to model, and pre-1976 homes lack the HUD certification most bank guidelines require. More than half of manufactured-home financing applications get denied industry-wide. Versara underwrites the property and the deal in-house instead.
How fast can Versara fund?
Applications get same-day review, and funding can happen in as little as 24 hours on qualified products because underwriting, draws, and closing all happen in-house.
Manufactured home financing in five states.
Versara
Private Money Loans
Flexible asset-based financing for deals that don't fit a conventional box.
Explore →
Versara
Rental & Buy-and-Hold
Hold the home you just financed. Longer-term loans qualified on the asset and its cash flow.
Explore →
Versara
Fix & Flip Loans
Purchase and rehab financing in one loan for investors who move fast.
Explore →
Ready when you are
Get your manufactured home deal quoted in 24 hours.
The loan request asks for the whole deal up front. An underwriter reads it the same day, and you'll have a decision within 24 hours.
of manufactured-home financing applications are denied industry-wide. Versara underwrites them in-house.
20%minimum down payment to secure a Versara loan, with terms sized 6 to 12 months.